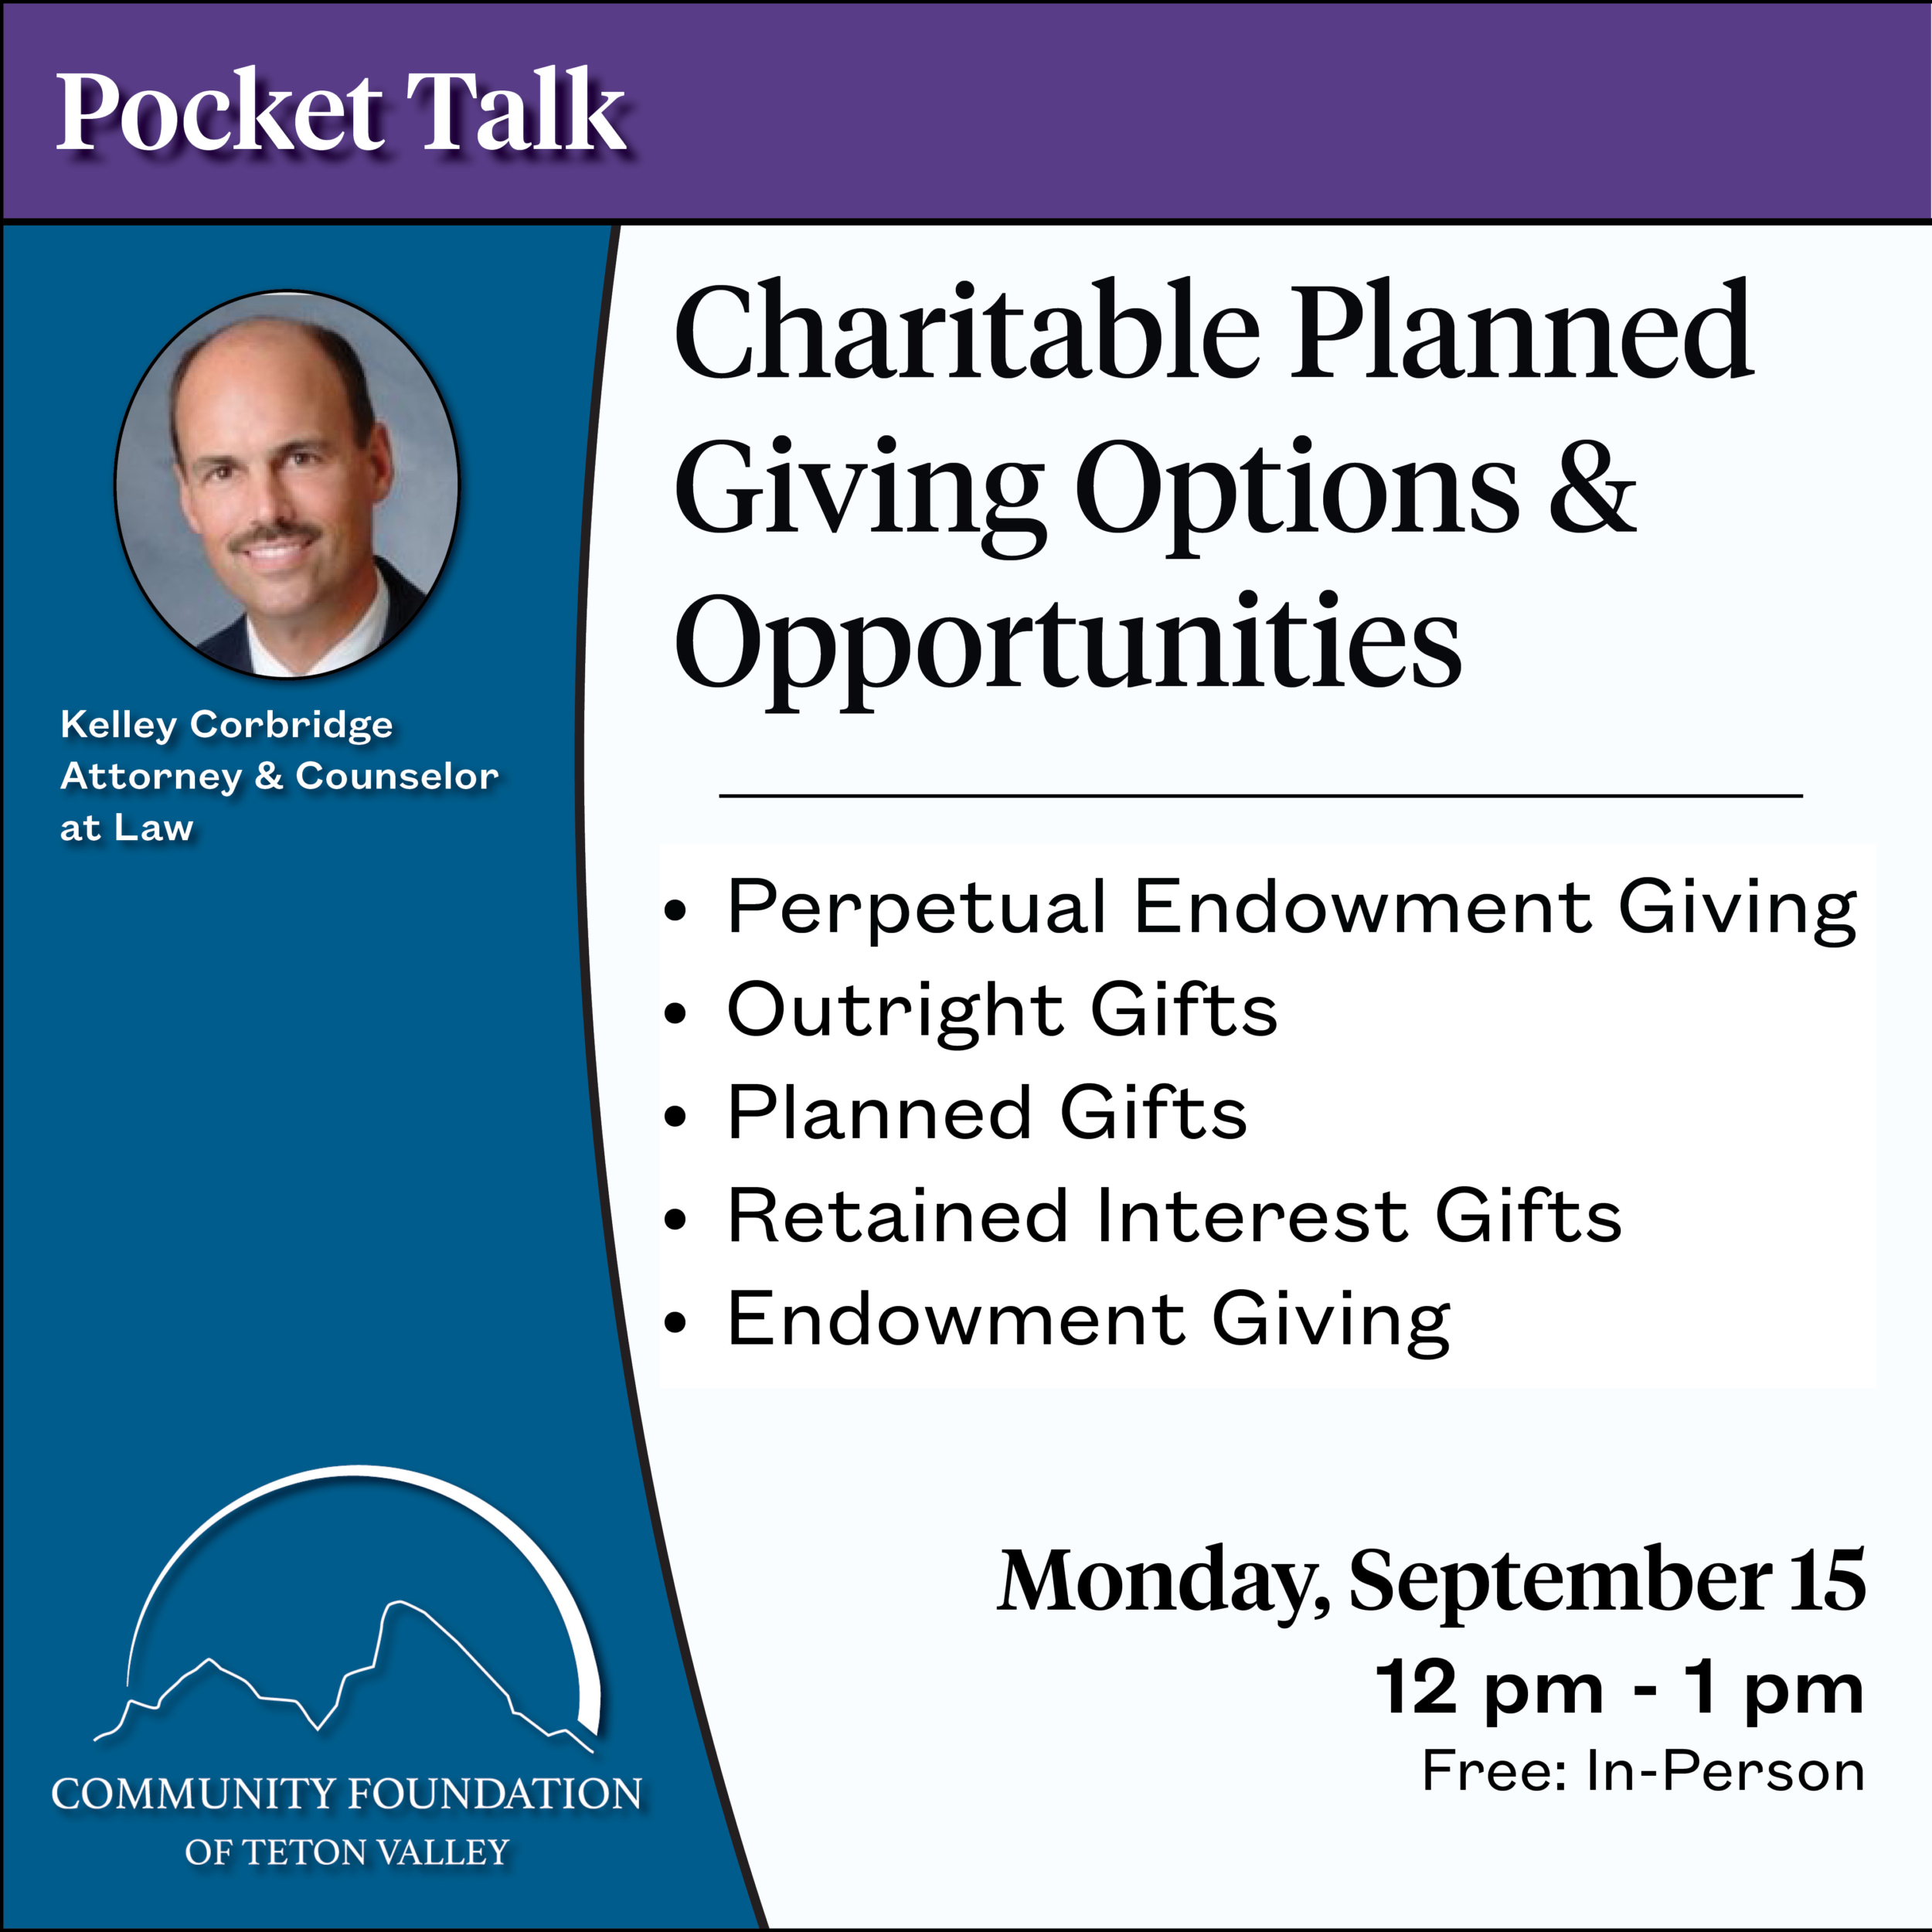
Charitable Planned Giving Options & Opportunities
Join this free and informative discussion with Kelley Corbridge on Charitable Planned Giving Options & Opportunities. This overview will give you understanding of:
- Perpetual Endowment Giving:
- Outright Gifts
- Planned Gifts
- Gifts with a retained interest
- Endowment vs Operational
- Outright Gifts:
- Directly to the Charity
- Income tax deduction
- If itemized and w/ 60% AGI limit for cash, 30% for appreciated securities, with carryovers)
- Out of estate for estate tax purposes
- IRA Direct Donation Option – Qualified Charitable Donation
- Age 70 ½
- $108,000 limit
- Certain types of Charities not available
- Private Foundations &
- Donor Advised Funds
- Options for special assets
- Fully paid Life Insurance
- Policy no longer required?
- Cash value equal to or close to death benefit?
- Avoid tax on accumulated earnings
- Capital Gains assets – gain avoided (stock, bonds, real estate, etc)
- Partnership with Community Foundation of Teton Valley
- Difficult to value assets
- Illiquid assets
- Pre-approval required
- Fully paid Life Insurance
- Planned Gifts:
- Will
- Trust
- Beneficiary designation
- i.e. IRA, 401-k
- Avoid potential double taxation
- Target taxable assets to charitable portion of estate plan
- i.e. step-up basis for other assets
- Potential “make-up” to family through life insurance trust
- Retained Interest Gifts:
- Income Stream for life or years, with balance to charity
- Charitable Remainder Trust
- Lifetime (may be multiple lives) or
- 20-year term
- Charitable Gift Annuity
- i.e. through Community Foundation of Teton Valley
- Avoid capital gains tax
- Increase income stream
- Charitable Lead Trust
- Income to charity for term of years
- Remainder to family
- Charitable Remainder Trust
- Impact of Interest Rates
- Higher the IRS interest rate, the higher the remainder interest and the lower the initial interest (Charitable Remainder Trust: higher income tax deduction and higher amount to charity – Charitable Lead Trust – opposite)
- Lower the IRS interest rate, the higher the initial interest and the lower the remainder interest (Charitable Remainder Trust: lower income tax deduction and lower amount to charity – Charitable Lead Trust – opposite)
- Donor may establish the interest rate so long as the actuarial charitable interest is at least 10% and annual payout interest rate is at least 5%
- Income Stream for life or years, with balance to charity
- Endowment Giving
- Long-term support of charitable organization (versus all into one-year’s operating budget)
- Teton Valley Community Foundation Partnership with endowment-oriented donor (instead of individual charities setting up their own foundation, with associated costs and compliance costs)
- A commonly favored option for charitable donors